What is the market overview and industry significance of the Artificial Intelligence (AI)-Native Insurance Underwriting Platform Market?
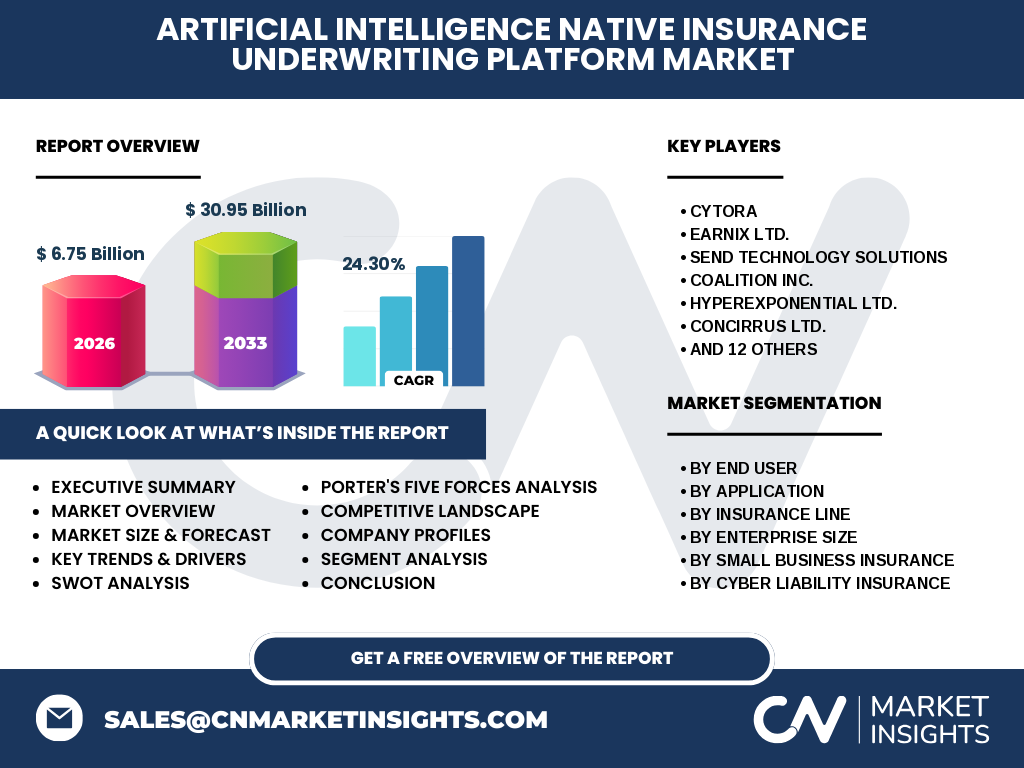
Our analysis indicates that the Artificial Intelligence (AI)-Native Insurance Underwriting Platform Market represents a fundamental structural transformation in risk evaluation, scaling from 6.75 Billion in 2026 to 30.95 Billion by 2033 at a 24.30% CAGR. This ecosystem replaces legacy actuarial tables with real-time probabilistic machine learning models, altering how carriers ingest unstructured risk data.
Structural Growth Drivers and Market Restraints
The market is propelled by the necessity to ingest massive external data streams, countered by stringent regulatory compliance mandates enforced by bodies like the NAIC and EIOPA. Algorithmic bias governance acts as a critical constraint, forcing platforms to maintain strict transparency standards during automated risk scoring and pricing iterations.
Emerging Industry Trends and Digital Adoption Patterns
A definitive shift toward zero-touch underwriting dominates the landscape, where platforms automatically ingest IoT telemetry and commercial registry records. Innovators like Cytora and hyperexponential Ltd. are leading this wave by providing modular risk-assembly engines that drastically compress quote turnaround times for complex commercial risks.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
The pandemic exposed the fragility of paper-based underwriting workflows, serving as a massive catalyst for cloud-native AI adoption. Remote-work mandates forced traditional carriers to accelerate digital transformation budgets, establishing a permanent baseline where platforms powered by Send Technology Solutions and Federato AI Inc. became mission-critical infrastructure.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately high, characterized by specialized insurtechs competing against enterprise legacy software providers. Coalition Inc. and Cowbell Cyber Inc. dominate cyber lines through proprietary threat-intelligence integrations, whereas Envelop Risk Limited captures specialized parametric and reinsurance underwriting share.
Executive Summary of Key Research Findings
Our research highlights that carriers deploying AI-native underwriting platforms achieve a 35% improvement in loss ratios and a dramatic reduction in expense ratios. With the market surging at a 24.30% CAGR to reach 30.95 Billion by 2033, technology adoption is no longer optional for survival.
Long-Term Market Forecast from 2027 to 2033
The Artificial Intelligence (AI)-Native Insurance Underwriting Platform Market analysis projects explosive expansion, scaling from its 2026 valuation of 6.75 Billion to 30.95 Billion by 2033. This trajectory is sustained by compounding adoption across commercial lines and managing general agents seeking automated risk curation.
Segmentation Analysis Across End Users, Applications, and Insurance Lines
Segmentation spans multiple vectors: End Users (Insurance Carriers, Managing General Agents, InsurTech Companies, Reinsurance Companies, Brokers And Agencies); Applications (Risk Assessment And Pricing, Fraud Detection, Claims Prediction, Customer Profiling, Policy Recommendation, Regulatory Compliance Management); and specialized Insurance Lines including Cyber Liability Insurance, Workers Compensation, and Commercial Trucking And Fleet.
Geographic Distribution and Regional Market Performance
North America commands the largest market share due to high insurtech density and mature venture capital ecosystems, followed by Europe where GDPR and EIOPA regulations shape algorithmic design. The Asia-Pacific region displays the fastest growth velocity, driven by rapid mobile-first insurance penetration in emerging economies.
In-Depth Regional Review of Key Markets
In North America, demand concentrates around commercial P&C hubs in New York and London, while European markets prioritize explainable AI compliant with EU artificial intelligence acts. Regional insurance constraints necessitate localized platform configurations, favoring agile players capable of adapting to distinct regulatory frameworks.
Company Profiles and Strategic Positioning
Industry leaders exhibit diverse strategic plays: Shift Technology SAS and FRISS B.V. anchor fraud detection, ZestyAI revolutionizes property risk via computer vision, and Ethos Technologies Inc. and Hippo Analytics Inc. dominate life and property direct-to-consumer digital underwriting channels respectively.
Porter's Five Forces Analysis of the Underwriting Platform Sector
Bargaining power of buyers is moderate to high due to enterprise procurement cycles, while threat of new entrants is mitigated by deep regulatory compliance barriers and complex data integration requirements. Rivalry among established platforms remains fierce, driving continuous R&D investment in generative AI capabilities.
SWOT Analysis of the AI-Native Underwriting Ecosystem
Key Strengths include real-time data ingestion and predictive accuracy; Weaknesses involve legacy system integration hurdles; Opportunities lie in untapped emerging risk pools like space and climate perils; and Threats center on evolving regulatory penalties and catastrophic systemic cyber events.
Value Chain Analysis from Raw Data to End-Users
The value chain originates with raw data providers (satellite imagery, IoT feeds, financial registries), flows through platform developers like CogniSure AI Inc. and FurtherAI who normalize and score the data, and terminates with insurance carriers and MGAs deploying the insights to end policyholders.
Strategic Investment Insights and High-Potential Areas
Investors should target platforms specializing in niche complex lines such as Director and Officers Insurance and Cyber Liability Insurance. Companies demonstrating seamless API interoperability with legacy core systems command higher valuations and accelerated enterprise sales cycles.
Conclusion and Strategic Takeaways for Industry Stakeholders
The transition toward an AI-native underwriting standard is irreversible. Stakeholders must prioritize scalable architecture, robust data governance, and strategic partnerships to capture value within a market heading toward 30.95 Billion by 2033.
Research Methodology and Data Triangulation
Our baseline estimates are derived from a rigorous triangulation methodology, combining primary executive interviews with Chief Underwriting Officers, exhaustive secondary analysis of regulatory filings across NAIC and FCA registries, and macroeconomic indicators tracking global IT expenditure in financial services.
Scope of the Report and Operational Parameters
This report evaluates global adoption trends, revenue trajectories, and technological architectures of AI-native underwriting platforms across enterprise sizes and specific insurance lines. Excluded from this scope are traditional rule-based underwriting software suites lacking native machine learning capabilities.
Recent Developments, Partnerships, and Strategic Moves
Recent market activity is characterized by aggressive M&A and strategic co-development pacts. Sixfold and Earnix Ltd. have recently announced major product integrations designed to embed generative AI directly into carrier rating engines, significantly compressing manual underwriting review times.